· Digital Footprint Check · Content Marketing · 16 min read
How Does Identity Theft Occur? Key Facts & Prevention Tips
Wondering how does identity theft occur? Learn common methods criminals use and how you can protect yourself from digital scams and physical theft.

Identity theft happens when a criminal gets your personal information — Social Security number, bank details, and the like — and uses it to commit fraud. The tactics range from stealing mail to complex digital scams, but the goal is the same: to pose as you for financial gain.
The Many Ways Your Identity Can Be Stolen
Think of your identity like a house. A thief can break in the front door with a stolen password, slip through a window with a phishing email, or rifle through your mailbox. Attackers probe every weakness, online and off.
Attackers mix high-tech hacks with old-school tricks that still work. Many incidents stem from weaknesses in digital systems, so understanding network security vulnerabilities is part of defending yourself. The scale is large: the Federal Trade Commission (FTC) saw over 1 million reports of identity theft in 2023 alone.
The infographic below gives an overview of how criminals break into that personal "house" of yours.
The threats come from all angles: digital scams, corporate data breaches, and physical theft, so your defense has to be layered too.
Common Methods of Identity Theft
Before building a defense, know what you're up against. Criminals update their methods, but most fall into a few categories, each designed to trick you into handing over information or to steal it directly.
The primary ways your identity gets compromised:
- Digital Deception: The classic phishing email, plus "smishing" (SMS scams) and "vishing" (voice-call scams). Crooks pose as your bank, a government agency like the IRS, or a company you trust to get your data.
- Data Breaches: Hackers break into the databases of large companies, healthcare providers, or agencies and steal personal information in bulk. Even perfect personal security can't prevent exposure in a breach.
- Malware and Skimming: Spyware can be installed on your computer to log every keystroke, including passwords. Physical "skimming" devices on ATMs or gas pumps copy the data off your card's magnetic stripe.
- Old-School Tactics: Thieves still go dumpster diving for unshredded documents, steal mail, and snatch wallets. These work because they're simple.
How Identity Theft Happens at a Glance
Here's a quick rundown of the most common methods criminals use.
| Method | What They Target | Primary Risk |
|---|---|---|
| Phishing/Smishing | Login credentials, financial details | You unknowingly give away your own data |
| Data Breaches | Social Security numbers, addresses, passwords | Your information is stolen from a third party |
| Malware/Spyware | Keystrokes, saved passwords, banking info | A malicious program steals data from your device |
| Card Skimming | Credit/debit card numbers and PINs | Your card information is cloned and used for fraud |
| Social Engineering | Personal details, security question answers | You are manipulated into revealing sensitive info |
| Mail & Physical Theft | Bank statements, pre-approved credit offers | Physical documents are stolen and exploited |
These are the foundational tactics in a thief's toolkit. By understanding how they operate, you're in a much better position to spot the red flags and protect yourself before it's too late.
Mastering the Art of Digital Deception
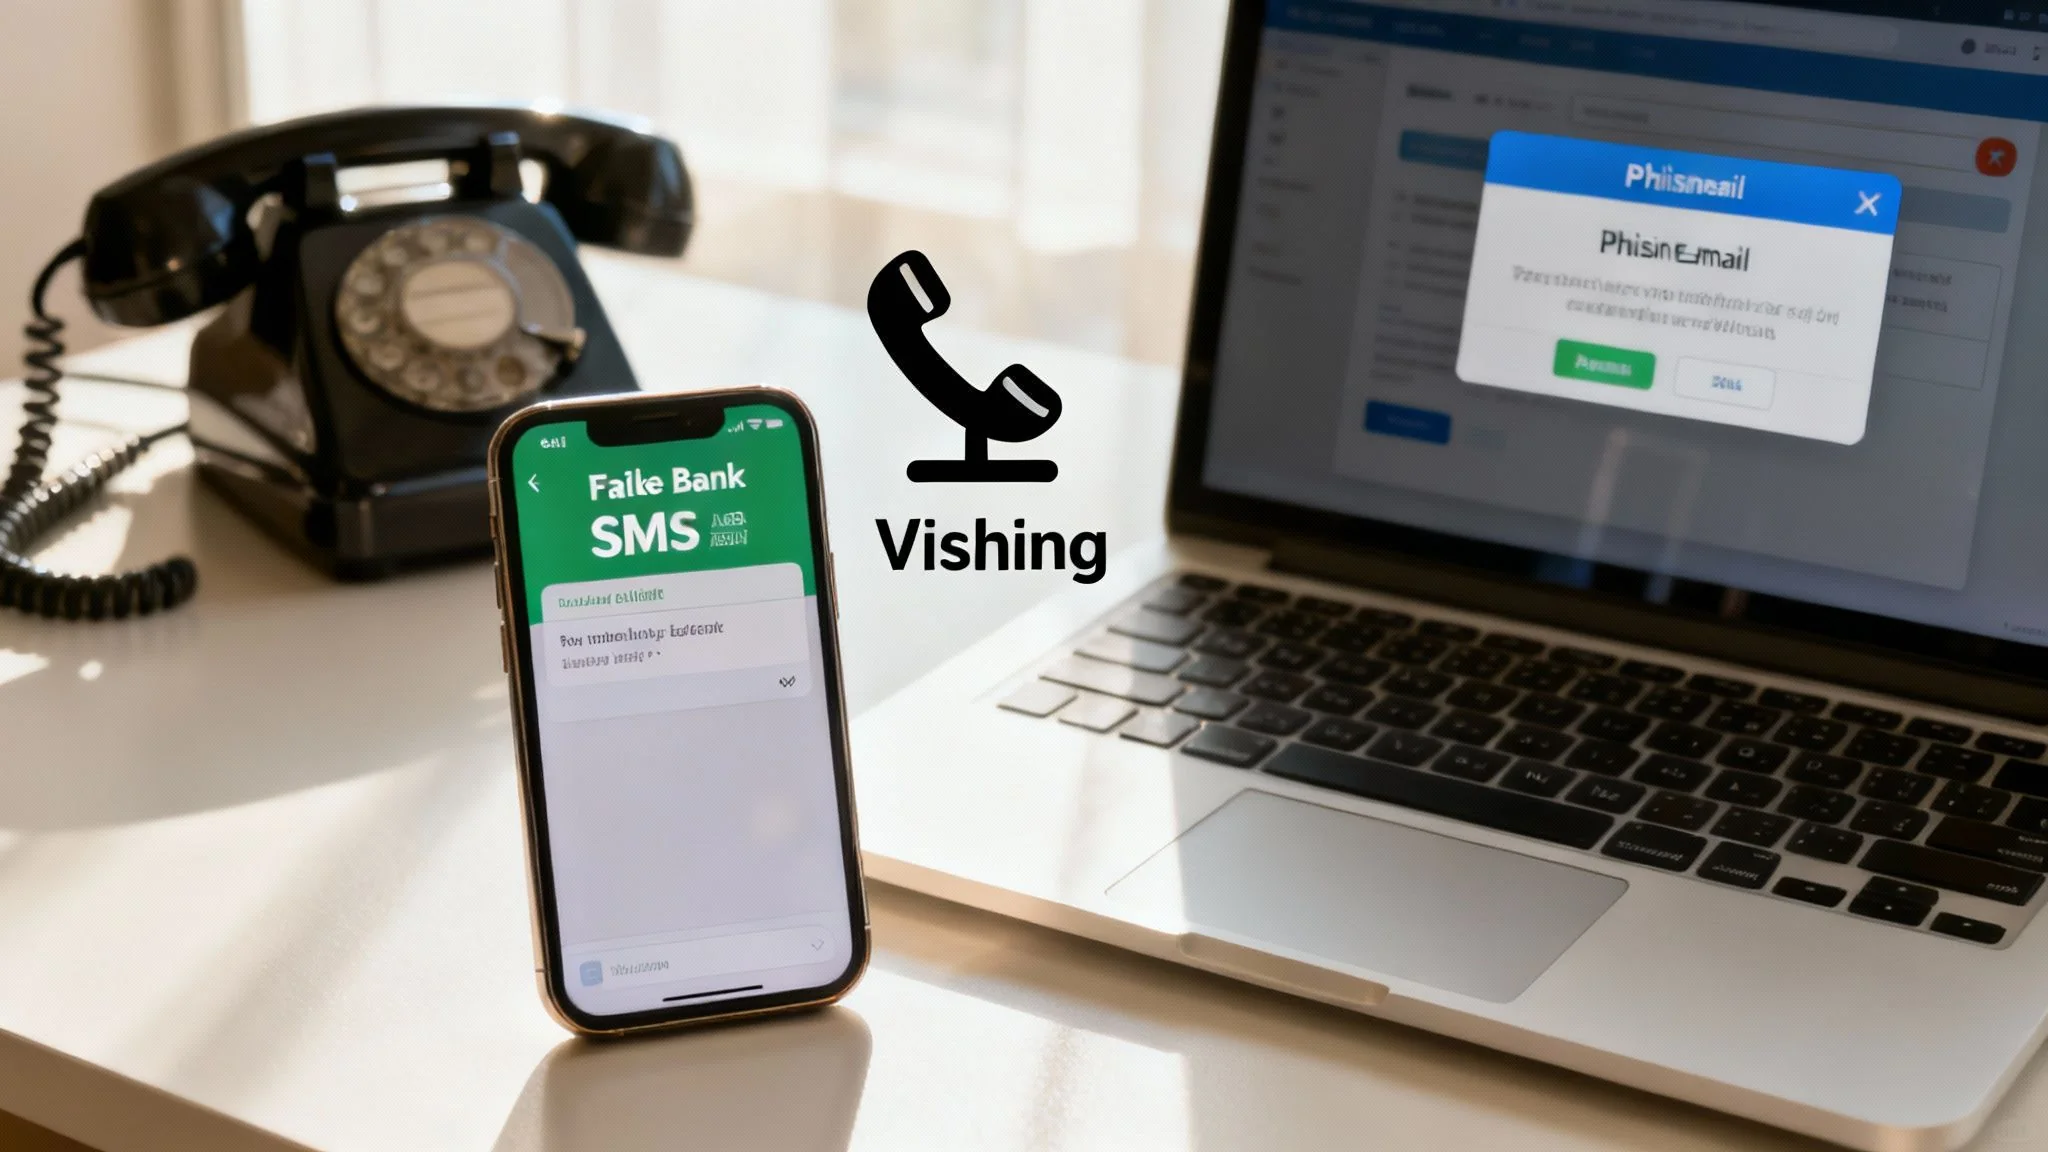
It’s an uncomfortable truth, but often the biggest security risk isn’t a weak password or a fancy firewall. It’s us. Human nature. Scammers have become masters of psychological manipulation, turning our own instincts against us to become their unwitting accomplices. This whole strategy has a name: social engineering.
Instead of trying to smash through digital walls, thieves play on your emotions. They’ll manufacture a sense of urgency, whip up a bit of fear, or pique your curiosity, all in an effort to get you to act before you have a chance to think. This is the engine that drives phishing, one of the most common roads to identity theft.
Phishing and Its Evolving Forms
At its core, phishing is a digital masquerade. Criminals put on a costume, pretending to be someone you know and trust. The classic example is that email that looks exactly like it’s from your bank, logo and all. It might scream about a “suspicious login” and give you a helpful link to “verify your account.” That link, of course, goes straight to a fake site built for one reason: to steal your login details.
But the con has grown way beyond simple emails. Today's attackers use every channel available to catch you with your guard down:
- Smishing (SMS Phishing): You get a text, maybe from a delivery service, claiming a package is held up by an unpaid customs fee. The link takes you to a slick-looking payment portal designed to harvest your credit card number.
- Vishing (Voice Phishing): An automated call says your Social Security number has been compromised. You're urged to press "1" to speak with an "agent" who will then ask for your personal information to "confirm your identity."
These tactics work because they prey on trust and urgency. A scammer pretending to be from the IRS can make even the most skeptical person sweat when they start threatening legal action.
The Power of Personalization
The most sinister scams are the ones made just for you. How does identity theft get so personal? Criminals dig through your public social media profiles, learning where you work, what you're interested in, and even the names of your family and friends. With this ammo, they can launch believable "spear phishing" attacks.
Imagine an email lands in your inbox from your boss. It mentions that project you just posted about on LinkedIn and asks you to click a link to review a new document. Because it feels so specific and personal, your natural defenses are down. This level of customization makes the scam almost impossible to spot.
If you have a sinking feeling your credentials have been stolen by one of these scams, you have to act fast. For a full rundown on what to do next, you can learn more about how to check if your email has been hacked and secure your accounts immediately. Ultimately, learning to recognize the psychological triggers these crooks use is your best defense against becoming their next target.
When Your Data Is Compromised at Scale
Sometimes, the answer to "how does identity theft happen?" has nothing to do with a mistake you made. You can follow all the rules—using strong passwords, spotting every phishing email, and shredding your mail—but still end up a victim.
This happens when the organizations you trust your data with, like corporations, government agencies, and even hospitals, suffer a massive data breach.
Think of it like this: a data breach is like a thief stealing the master key to an entire apartment building. It doesn't matter how secure your individual apartment lock is. The criminal now has a way to bypass it and get into every unit. Suddenly, the personal information of thousands or even millions of people is exposed all at once. For more on these large-scale incidents, you can explore our guide that explains what is a data breach and its impact on you.
From Corporate Servers to Criminal Marketplaces
When hackers break through a company's defenses, they don't just steal a few records; they hit a rich source of sensitive information. This raw data is often bundled up and sold on the dark web, creating a ready supply of identities for any criminal to buy and exploit.
The stolen information can include a whole range of your personal details, giving a thief everything they need to impersonate you.
- Full Names and Addresses: The basic building blocks for creating fake accounts.
- Social Security Numbers: The skeleton key to opening new lines of credit and filing fraudulent tax returns in your name.
- Login Credentials: Usernames and passwords that criminals test on other websites, hoping you reused them.
- Financial Information: Credit card numbers and bank account details, ready for a shopping spree.
This stolen data fuels a massive underground economy. Criminals buy these "fullz"—a slang term for a full package of an individual's identifying information—to carry out all sorts of fraud. When data is compromised at this scale, it's critical for organizations to have a solid data breach response plan to limit the damage and protect the people affected.
The Staggering Scale of Data Exposure
The sheer volume of exposed data is almost hard to believe. Cyber attacks that use stolen credentials are a primary driver of identity theft. In just one recent year, a shocking 107 billion records were exposed across the globe.
This surge was largely fueled by attacks where criminals simply used stolen login details to walk right through the front door of corporate systems. You can discover more insights about these findings on cyber risk at Constella.ai.
This isn't just a hypothetical problem. When a large retailer or a credit bureau gets hit, your data could be in the hands of criminals long before you ever get a notification letter in the mail. This is exactly why ongoing monitoring for your information on the dark web is so important.
Uncovering the Invisible Threats
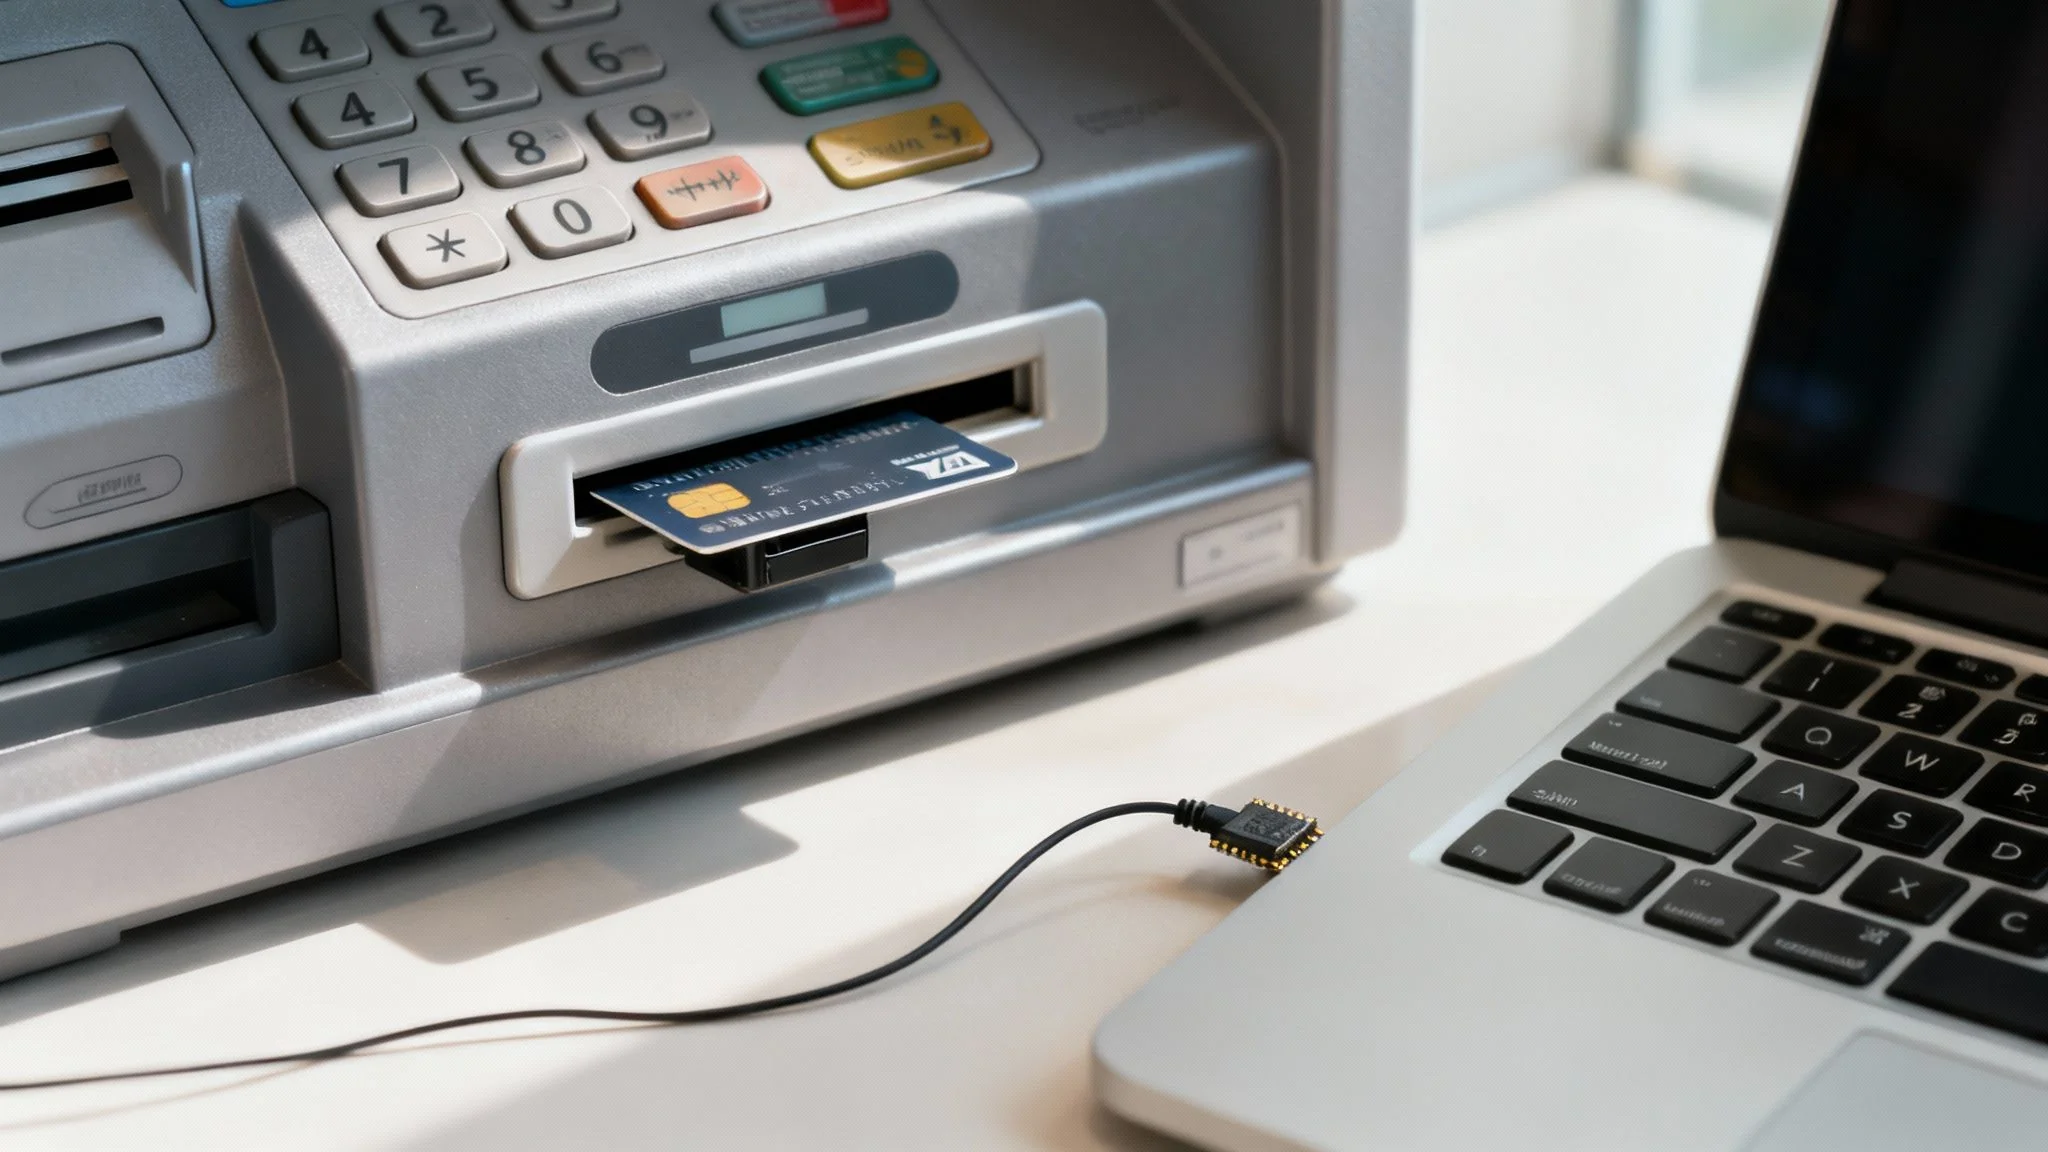
It’s easy to think of identity theft as something that happens through a sketchy email or a massive corporate data breach. But some of the most successful methods are far more subtle, operating silently in the background of your digital and physical life.
These are the hidden tools that turn your own devices and daily routines against you. Malicious software, better known as malware, is a perfect example. It works without you ever clicking a suspicious link, almost like a thief planting a bug in your home to secretly record everything you say and do.
When Your Own Device Betrays You
Once malware gets onto your computer—often hidden inside a seemingly harmless download—it can start stealing your data immediately. Criminals have a whole toolkit of these digital spies, each designed for a specific job.
The two you’ll run into most often are:
- Keyloggers: This kind of malware is brutally simple and effective. It secretly records every keystroke you make, from your bank password to private messages you send.
- Spyware: This is a wider category of malware that’s all about monitoring your activity. It can snap screenshots, track the websites you visit, and even turn on your webcam, sending all of it back to a criminal’s server.
Think of malware as the digital equivalent of someone looking over your shoulder every time you use your computer. The goal is to capture your most sensitive information at the exact moment you enter it.
Physical Threats in a Digital World
The threat isn’t just lurking on your computer. Criminals have also perfected low-tech ways to steal high-tech data, especially on your credit and debit cards. This is where skimming comes into play.
A skimming device is a small gadget that criminals physically attach to a real card reader, like the ones on an ATM or a gas pump. When you swipe your card, the skimmer reads and stores the data from the magnetic stripe.
To complete the scam, they’ll often place a tiny, hidden camera nearby to record you punching in your PIN. With your card data and your PIN, they have everything they need to create a clone of your card and start draining your account.
These skimmers are designed to blend in and look like a normal part of the machine, which makes them difficult to spot. Before you swipe, always give the card reader a quick wiggle. If it feels loose, bulky, or just doesn't look right, it could be a skimmer. Protecting yourself requires staying vigilant in both your digital and physical worlds.
The Alarming Rise of Synthetic Identities
Some of the most damaging identity theft schemes don't involve hijacking one person's life, but creating a brand new, fake one. This is synthetic identity fraud, a particularly nasty method that’s much harder for anyone to spot than traditional identity theft.
Instead of just taking over your existing accounts, criminals play the role of a digital Dr. Frankenstein. They stitch together bits and pieces of real information with fabricated details to build a "ghost" identity that doesn't belong to any single, real person.
Building a Ghost Identity
The whole process usually kicks off with one critical piece of real data: a Social Security number (SSN). Fraudsters love to target the unused SSNs of children, the elderly, or even incarcerated individuals because these numbers aren't typically attached to active credit files.
Once they have a valid SSN, they start building the fake persona around it:
- A made-up name.
- A fake date of birth.
- A bogus address, maybe pointing to a vacant lot or a P.O. box.
Armed with this new synthetic identity, the criminal applies for credit. They'll probably get rejected at first, but that's part of the plan. Just applying is enough to get a new credit file started under the fake name. From there, the thief patiently builds a positive credit history for their ghost, sometimes by adding it as an authorized user on another account or taking out small, easy-to-manage loans.
This slow, methodical cultivation is what makes synthetic fraud so dangerous. Over time, the identity starts to look legitimate, fooling lenders and credit bureaus into thinking it's a real person with a solid financial track record.
The Inevitable 'Bust Out'
After months, or even years, of carefully building this fake credit history, the criminal pulls the trigger on the final phase: the "bust out." They leverage the synthetic identity's now-excellent credit score to max out every line of credit they can get their hands on—credit cards, personal loans, car loans—all at once.
Once the money is in their pocket, they simply vanish. The financial institutions are left chasing a ghost, trying to collect money from someone who never actually existed. The trail goes cold. This isn't just a petty scam; the global shift to digital transactions has made these schemes effective. In fact, over 70% of identity fraud now happens in digital channels, a trend that's only going up. You can dig deeper into these numbers with insights on identity fraud at Snappt.com.
The fallout from synthetic identity fraud is massive. It leaves banks with billions in losses and has become one of the most significant ways identity theft happens today.
Why Old-School Theft Still Works
In an age of sophisticated cyberattacks, it’s easy to forget that some of the most effective identity theft methods are surprisingly low-tech. While digital threats grab all the headlines, criminals don't always need complex malware when they can just rifle through your mailbox.
This hands-on approach targets your physical documents and belongings directly. A stolen wallet or purse, for instance, is an absolute rich source for a thief. It often holds a driver’s license, credit cards, and debit cards—everything they need to start making fraudulent purchases or trying to access your bank accounts before you even notice it’s gone.
From Your Trash to a Thief’s Treasure
One of the most common old-school tactics is good old-fashioned dumpster diving. It sounds gritty, but for an identity thief, an unshredded document is a jackpot. Many people simply toss out sensitive mail without a second thought.
These thieves patiently sift through garbage to find discarded items that paint a surprisingly detailed picture of your financial life:
- Pre-approved credit card offers that they can intercept and activate.
- Bank and investment statements revealing account numbers and balances.
- Medical bills or insurance explanations that contain policy numbers and other personal identifiers.
- Old utility bills that help them confirm your name and address for new fraudulent accounts.
The information gathered from a single bag of trash can be enough for a criminal to open new lines of credit, file a fake tax return, or piece together the answers to your security questions.
Protecting Your Physical World
Locking down your physical information is every bit as critical as using strong passwords. A few simple habits can shut down these low-tech avenues of attack and make a huge difference in your risk level.
First, invest in a cross-cut shredder. Seriously. Never, ever throw away any document with personal or financial information without shredding it first. This includes all that junk mail, especially the credit card offers.
Second, think about your mail security. If your mailbox doesn't lock, consider sending sensitive documents directly from the post office. When you’re away from home, ask the postal service to hold your mail. These small steps are a powerful reminder that our physical security is the true foundation of our digital safety.
Frequently Asked Questions About Identity Theft
After diving into the ways thieves operate, you probably have a few lingering questions. It's one thing to understand the threat, but knowing exactly what to do next is what really counts. Let's tackle some of the most common concerns to help you turn that knowledge into action.
What Is the First Thing I Should Do If My Identity Is Stolen?
Your first move is damage control. The absolute first thing you should do is head over to IdentityTheft.gov, the official recovery site run by the Federal Trade Commission (FTC). They'll walk you through a personalized plan based on your specific situation.
At the same time, you need to contact one of the three major credit bureaus—Equifax, Experian, or TransUnion—and place a fraud alert on your credit file. This is like putting up a giant red flag for lenders, warning them that someone might be trying to open accounts in your name and making it much harder for thieves to succeed.
Is It Safe to Use Public Wi-Fi?
Using a public, unsecured Wi-Fi network is a huge gamble. Think of it like shouting your bank password across a crowded coffee shop—you never know who's listening. Scammers on the same network can easily intercept your data in what’s called a "man-in-the-middle" attack, grabbing everything from your passwords to your credit card details.
If you have to use public Wi-Fi, try to avoid logging into anything sensitive, like your bank or main email account. For real security, your best bet is a reputable Virtual Private Network (VPN). A VPN encrypts your connection, scrambling your data into an unreadable mess for any would-be snoops.
How Do I Protect My Child from Identity Theft?
Child identity theft is particularly nasty because it can fly under the radar for years. Often, the damage isn't discovered until a teenager applies for their first job, car loan, or college aid. The best defense is to be fiercely proactive with their information.
Start by guarding their Social Security number (SSN) like a hawk. Whenever you're asked for it, always question why it's needed and how it will be stored securely. And of course, keep crucial documents like their birth certificate and SSN card locked away safely.
The single most effective step you can take is to proactively freeze your child's credit with all three credit bureaus. Since a child shouldn't have a credit file, a freeze prevents one from being created without your explicit permission, stopping thieves in their tracks.
Keeping your family safe means getting a handle on your entire online presence. For a deeper look, it's worth learning about identity theft protection and the significance of conducting an online digital footprint check to see exactly where your family's information might be exposed.
Are you concerned about where your personal information might be exposed online? Digital Footprint Check scans the web to find your data, alerts you to risks like data breaches, and provides clear steps to protect your identity. Take control of your online safety and see your free report today at https://www.digitalfootprintcheck.com.